A submission arrives with an ACORD form, a spreadsheet, two loss runs, and an email that says, “Please use the attached revised version.”
The AI platform extracts almost everything correctly. Then it quietly misses the one value that matters.
That is where the real evaluation begins.
For teams buying AI insurance submission processing software, extraction accuracy is only the first test. The harder questions come next. What does the system do when information is incomplete? What happens when documents disagree, or confidence drops? Can an underwriter see why a value was chosen?
This guide outlines eight checks for CUOs, MGA leaders, and underwriting operations teams to run before choosing a platform.
If you are evaluating AI insurance submission processing software, don't judge it on extraction accuracy alone. Test what it does when a submission is messy. Before you book a demo, check these eight things:
- 1.Multi-channel ingestion
- 2.Complex document handling
- 3.Source evidence
- 4.Confidence and exception handling
- 5.Underwriting rules
- 6.Intelligent routing
- 7.System integration
- 8.Audit trail
Next step: Run these eight checks against your current process with us.
Put Your Submission Process to the Test
See where automation can reduce manual work, surface exceptions, and accelerate submission handling.
What Is AI Insurance Submission Processing Software Designed to Do?
It takes a broker's submission package and turns it into work an underwriter can act on. The steps are ingestion, document classification, data extraction, validation, routing, and human review.
The goal is not to turn documents into data. The goal is to turn an unstructured submission into a validated, underwriting-ready workflow.
That difference shapes every question in this guide. Insurance submission software that only extracts fields leaves the hardest work to your team. Software that validates, flags, and routes removes it.
What Should Insurance Submission Software Automate?
Automate preparation, not accountability
What should happen before underwriting review?
Document capture, classification, extraction, completeness checks, and data normalization. This is repeatable work, and it is where submission intake automation recovers the most time.
Which tasks should stay with people?
Underwriting judgment, exceptions, ambiguous evidence, appetite interpretation, and final decisions. A human-in-the-loop design keeps these with the underwriter.
| Stage | Manual Workflow | AI-Enabled Workflow | Human Responsibility |
|---|---|---|---|
| Intake | Read emails, download attachments | Ingest and classify the full package | Confirm unusual packages |
| Data Entry | Re-key fields into systems | Extract and normalise fields | Review low-confidence values |
| Completeness | Chase brokers by memory | Flag missing items automatically | Decide what to request |
| Routing | Manual triage | Rules-based prioritisation | Handle escalations |
| Decision | Underwriter judgement | Decision support with evidence | Own the decision |
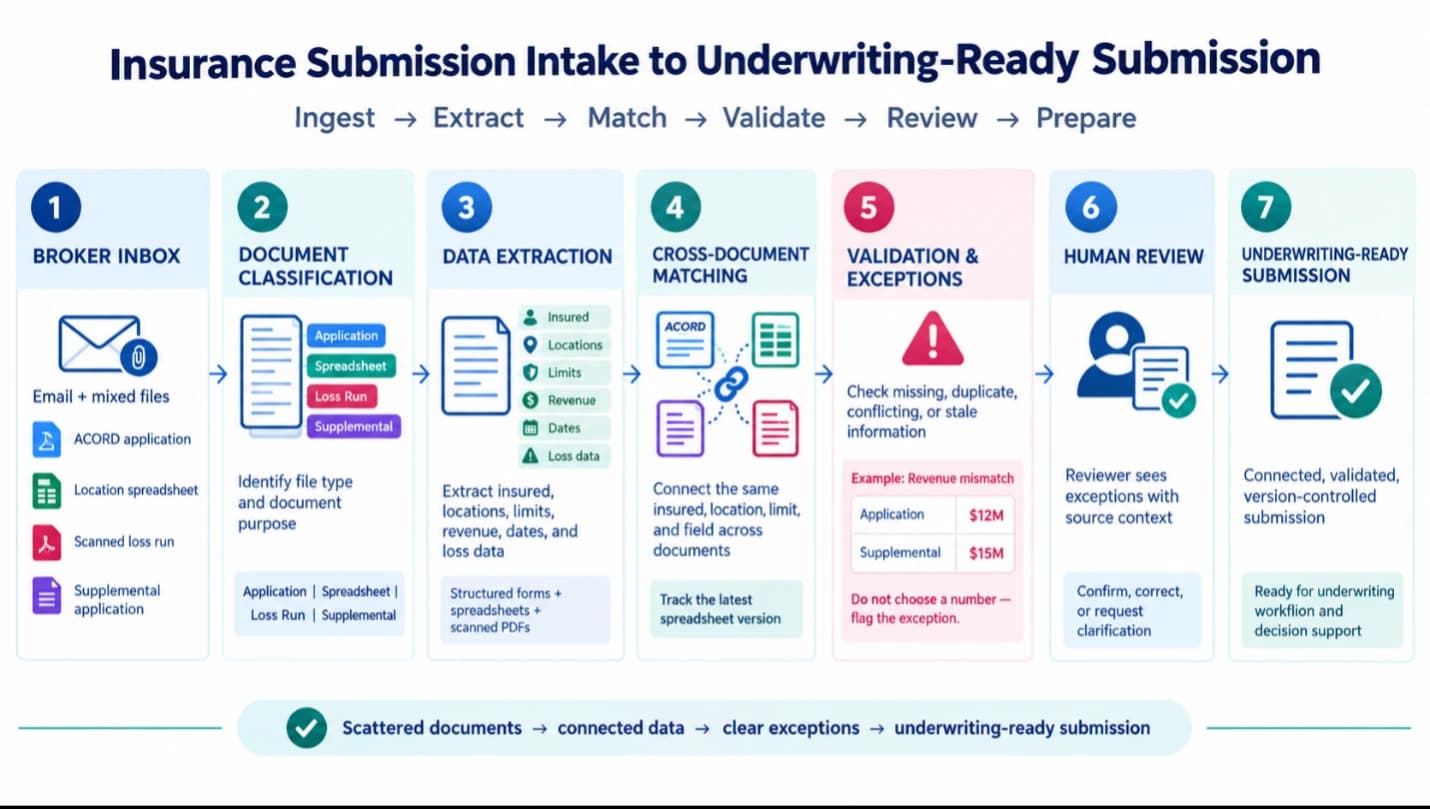
How Does It Work Across a Real Submission?
Consider a "messy Tuesday" submission. This is an illustrative scenario, not a client case study.
A broker emails an ACORD application, a spreadsheet of locations, a scanned loss run, and a supplemental application. A later email says the spreadsheet has been revised. The revenue figure on the application does not match the one in the supplemental.
Here is how a well-designed workflow handles it.
Can it ingest mixed formats?
It should accept emails, PDFs, ACORD forms, spreadsheets, and scanned documents in one package. It should not require the broker to change how they send work.
Can it connect information across documents?
It should link the same insured, location, or limit across files. It should also know which spreadsheet version is current.
Can it find missing or conflicting information?
Here it should surface the revenue mismatch rather than pick a number. A clean demo tells you very little about how the platform behaves when two documents disagree.
Which Features Matter Most When Evaluating Insurance Submission Software?
Every vendor claims accuracy. What separates platforms is how they behave on the failure path. These eight checks form a practical framework. Each one follows the same logic: what you see, what it means, what to ask.
1. Does it support multi-channel ingestion?
Submissions come from email, portals, and broker platforms.
Ask: which channels are supported, and what happens to an attachment it cannot read?
2. Can it process complex insurance documents?
Loss runs, statements of values, and supplemental applications vary widely by carrier and broker.
Ask: can we test it on our own hardest document types?
3. Does it preserve source evidence?
An extracted value is only useful if an underwriter can see where it came from.
Ask: does every field link back to the page and location it was read from?
4. How does it handle confidence and exceptions?
Confidence scoring tells the system when to proceed and when to stop.
Ask: what happens below the threshold, and who receives the exception?
5. Can it apply underwriting rules?
Appetite rules and guidelines should sit in configurable logic, not in an underwriter's memory.
Ask: who maintains the rules, and how quickly can they change?
6. Can it route submissions intelligently?
Routing should reflect appetite, complexity, line of business, and workload.
Ask: can routing logic be explained to an underwriting manager?
7. Can it integrate with existing systems?
Standalone tools create new silos.
Ask: which systems does it connect to today, and which need custom work?
8. Does it provide an audit trail?
Every extraction, override, and approval should be recorded and replayable.
Ask: can we reconstruct how a decision was reached six months later?
Test These When Evaluating AI Insurance Submission Processing Software: Quick Glance
| Criterion | What to Test | Red Flag | Evidence Required |
|---|---|---|---|
| Ingestion | Mixed packages, scans, revised versions | Only clean PDFs shown | Run on your own submissions |
| Document Handling | Loss runs, SOVs, supplementals | “Any document” with no examples | Field-level results by document type |
| Source Evidence | Click-through from field to source | Values shown without origin | Live traceability demo |
| Confidence & Exceptions | Low-confidence and missing data | One accuracy number only | Exception rate and review volume |
| Rules | Appetite and guideline changes | Changes need vendor tickets | Configuration walkthrough |
| Routing | Priority and assignment logic | Opaque scoring | Explainable routing logs |
| Integration | PAS, workbench, CRM connections | High-level claims only | Named reference integrations |
| Audit Trail | Overrides, approvals, replay | Logs only for admins | Sample audit export |
How Should Buyers Test AI Accuracy Before Choosing a Platform?
Don't ask a vendor for an accuracy figure. Run your own test.
Build a representative set of submissions from your own history. Include clean files, messy files, scanned documents, contradictory values, missing fields, unusual formats, multiple versions, and incomplete packages. Then measure AI document processing results against what your underwriters would have entered.
A vendor-controlled demo cannot tell you this. A test set drawn from your own inbox can.
How Should Submission Software Handle Missing or Conflicting Data?
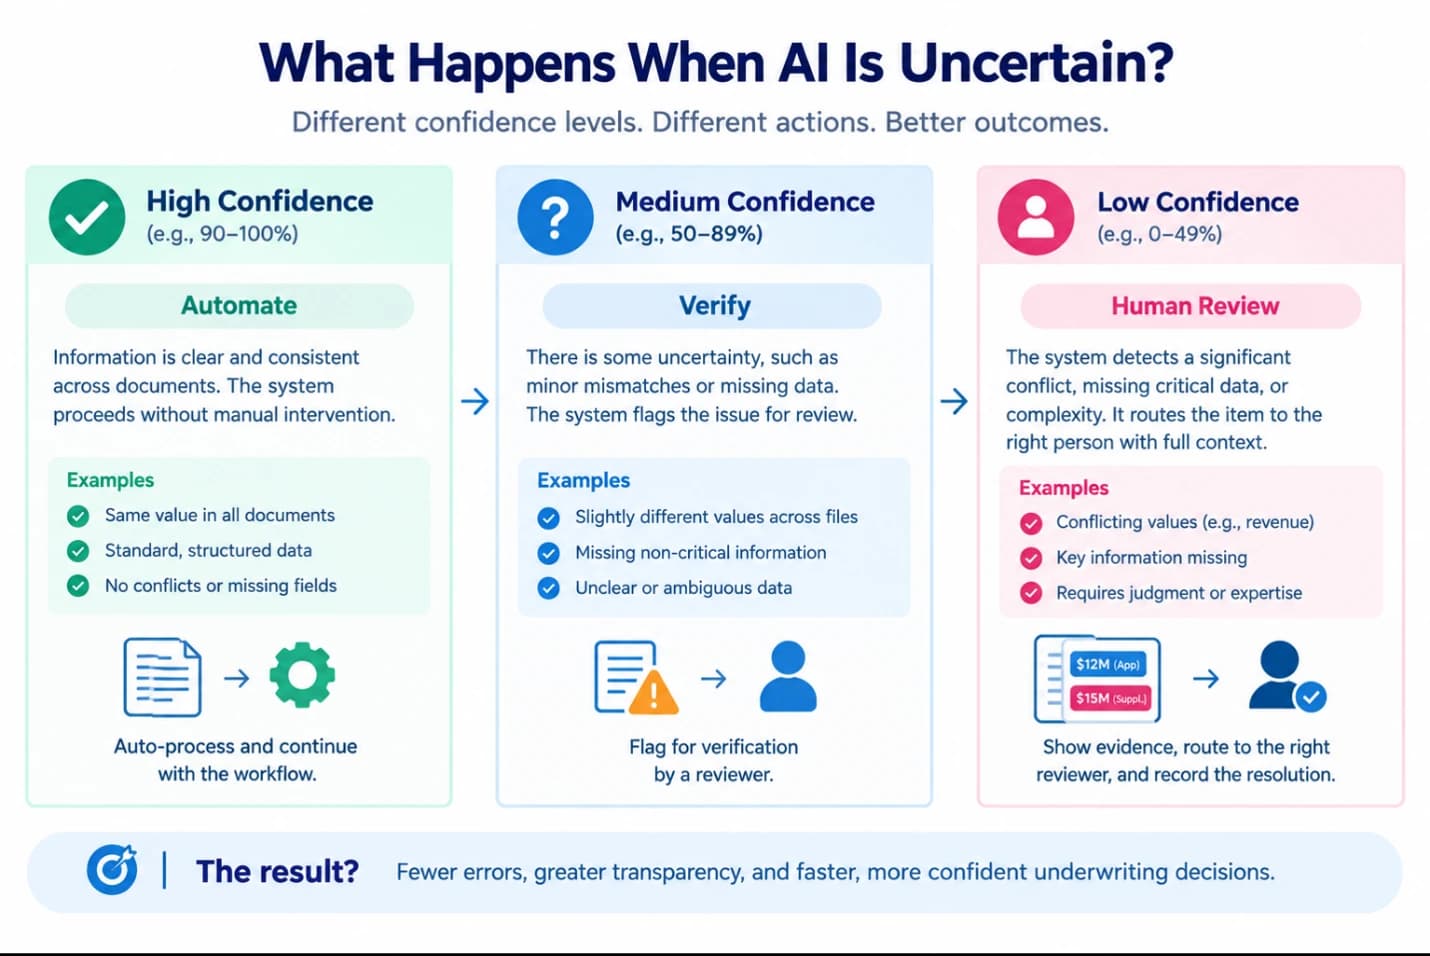
There are three possible behaviors.
- Worst: the system silently picks a value.
- Better: it flags the discrepancy.
- Best: it flags the discrepancy, shows the source evidence for each value, routes it to the right reviewer, and records the resolution.
Ask every vendor to show all three moments live. If they can only show the first, you have learned something important about how the platform treats uncertainty.
What Integration Capabilities Should Insurance Submission Software Provide?
Integration is a workflow question, not only an API question. A connection that pushes data into a system without preserving evidence or exceptions moves the problem rather than solving it.
Check four things:
- Policy administration system: can it write validated data into your PAS, and can it read from it?
- Underwriting workbench: does the submission arrive ready for review?
- CRM and document repositories: can it link to broker and account records?
- APIs: are they documented, versioned, and available to your team?
The best platforms work alongside existing systems rather than replacing them. Once submission data is validated, quote preparation is often the next bottleneck. That is where insurance quoting automation becomes the logical next workflow layer.
How Important Are Auditability and Human Oversight?
They are essential, and regulators agree. The NAIC adopted its Model Bulletin on the use of AI systems by insurers in December 2023 and continues to work on evaluating AI and third-party models.
Look for human approval steps, source provenance, decision logs, exception records, and replayability. Software does not make an insurer compliant on its own. These controls can support an insurer's governance and audit requirements
Does AI Submission Processing Replace Underwriters?
No. The stronger model automates repetitive preparation, validation, and routing. Underwriters keep control of judgment and exceptions. Any vendor promising fully autonomous underwriting without explaining its controls should raise a flag.
How Should an MGA or Carrier Calculate Submission Automation ROI?
Start with capacity:
Recoverable hours = monthly submissions × minutes per submission ÷ 60 × share automated, minus exception review time
An illustrative example: 1,000 submissions a month at 30 minutes each is 500 hours. If 60% of that work is automated, that is 300 hours. Subtract the time spent on exceptions to get the real figure.
Be careful with what recovered hours mean. They do not automatically equal headcount savings. They may show up as more submissions handled, faster quote turnaround, or more underwriting capacity.
Next step: Calculate what your backlog is costing with our ROI Calculator.

What Should an Insurance Submission Software RFP Ask Vendors?
Use these questions in any vendor evaluation of insurance submission processing software:
- Data: Which formats are supported? How is source provenance kept?
- Accuracy: How is accuracy measured? How is confidence calculated?
- Exceptions: What happens when the system is unsure? Who receives the exception?
- Integration: Which APIs and systems are supported today?
- Governance: Are all actions logged? Can decisions be reviewed?
- Implementation: How long does deployment take? What configuration is required?
- Commercials: How is pricing metered? What happens when volume doubles?
What Are the Red Flags?
- The demo uses unusually clean documents. Ask for your messy ones.
- The vendor shows accuracy but no exceptions. Ask what the system does when it is wrong.
- Human review is vague. Ask who reviews what, and where.
- Integrations stay high-level. Ask for named systems and reference customers.
- There is no clear audit trail. Ask for a sample export.
- “Fully autonomous” is promised without controls. Ask what stops a bad decision.
What Should a Real-World Pilot Test?
Run the pilot on historical and difficult submissions from multiple brokers, in multiple formats, including incomplete files, conflicting information, and edge cases.
Score it on eight dimensions: extraction quality, exception quality, review burden, workflow completion, integration reliability, auditability, user acceptance, and turnaround time.
Agree on the scorecard before the pilot starts, not after.
Next step: Bring a representative submission workflow and pressure-test it against the framework.
The 30-Day Insurance Submission Software Pilot Scorecard
| Evaluation Dimension | What to Test | Suggested KPI / Measure | What Good Looks Like | Pilot Score |
|---|---|---|---|---|
| 1. Extraction Quality | Test ACORD forms, spreadsheets, loss runs, supplementals and scanned documents | Field-level accuracy; critical-field accuracy | Critical data is extracted accurately with minimal manual correction | ☐ / 5 |
| Exception Quality | Introduce missing, conflicting and low-confidence information | % of meaningful exceptions identified; false alerts | Surfaces issues instead of silently choosing or overwriting values | ☐ / 5 |
| Review Burden | Measure how much human review is still required | Minutes of review per submission; % requiring intervention | Underwriters review exceptions rather than recheck the entire submission | ☐ / 5 |
| Workflow Completion | Run submissions from intake through routing / underwriting-ready output | % of submissions completed end-to-end | Handles the full workflow without significant manual workarounds | ☐ / 5 |
| Integration Reliability | Test connections with PAS, CRM, workbench and other systems | Successful transactions; error rate; failed handoffs | Data moves reliably between systems without duplicate entry | ☐ / 5 |
| Auditability | Trace extracted values, changes, overrides and approvals | % of key actions traceable; audit completeness | Every important decision or change has a clear evidence trail | ☐ / 5 |
| User Acceptance | Have underwriters and operations users work with real outputs | User satisfaction; adoption rate; usability feedback | Users trust the workflow and can understand and act on exceptions | ☐ / 5 |
| Turnaround Time | Compare current process with AI-enabled workflow | Average processing time; time to underwriting-ready | Meaningful reduction in submission handling time | ☐ / 5 |
| Overall | Evaluate performance across all eight dimensions | Total score / 40 | Meets the pre-agreed pilot success threshold | __/40 |
Where Does an Agentic Approach Fit?
Document extraction reads a submission. A decision-aware workflow acts on it: it applies rules, routes work, waits for approval, and records every step.
Xignifi, a Decision Intelligence platform, is built around that second layer. Its insurance agents connect document intelligence, decisioning, and orchestration, with human approval gates and auditable reasoning at each step. See how this applies to submission triage and customer results.
Put Your Submission Workflow to the Test
Bring a real submission and see where AI can automate intake, surface exceptions, and support your underwriters.
What Buyers Ask About AI Insurance Submission Processing Software
AI insurance submission processing software ingests broker submissions, classifies documents, extracts and validates data, flags gaps, and routes each submission to the right underwriter. Extraction is only the first step. A platform that stops there leaves validation, exceptions, and routing with your team, so ask what happens after the data is read.
Editor's Note: What Separates Reliable Submission Software from a Good Demo
When we sit down with underwriting teams, the conversation rarely starts with extraction. It starts with one submission that went wrong: a revised spreadsheet nobody noticed, or a loss run that contradicted the application.
That is a useful place to begin. Almost any platform can read a clean document. What separates one from another is how it behaves at the edge of its own confidence. Does it stop and say so, show where each value came from, and hand the decision to the right person? Or does it move quickly and leave the underwriter to find the problem later?
So our advice on AI insurance submission processing software is simple. Bring your hardest submission to the evaluation, not your average one. Ask to see the exception, the source evidence, and the approval step. If the platform handles those well, the rest tends to follow.
Automation should take the preparation off your underwriters’ desks. The judgment stays with them.
Bring One Difficult Submission
Bring one real submission workflow to Xignifi. We’ll map the intake, exceptions, approvals, and downstream actions, so you can see what should be automated before you commit to a platform.
Talk to Xignifi
Bring Your Hardest Submission
See how your real submission could move from broker inbox to underwriting-ready with the right exceptions, approvals, and human decisions built in.
Map Your Submission Workflow